Ideas
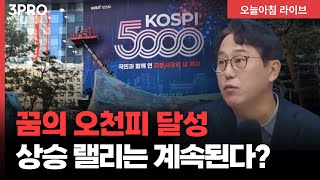
Historic KOSPI 5000 breakout likely continues.
KOSPI's first move above 5,000 is a historic regime shift; with new retail money and favorable flows, the index is likely to continue higher rather than mark a final top.
Institutions rotate into beaten-down Korean small caps.
After a round-number index breakout, institutions that underperformed the index must hunt for performance in under-owned, beaten-down small and mid caps, driving volume and short squeezes in Korean small/mid-cap equities.
Hyundai Motor trend intact despite foreign selling.
Individual investors are rotating into Hyundai Motor from Samsung Electronics while foreign investors take profits, but the uptrend is not broken and the stock may have another upward move after this supply shift.
Battery sector rebounds on institutional short covering.
The battery sector is rebounding strongly from a depressed base as institutions enter beaten-down second-battery names, triggering short covering; if the index consolidates, laggards can still rise.
Samsung SDI squeeze and institutional buying continue.
Samsung SDI surged nearly 19% on short covering and institutional/foreign buying after being excessively depressed; the move signals a large-cap battery short squeeze.
L&F backlog supports battery catch-up trade.
L&F has order backlog and a tight consolidation; it is participating in the battery-sector rebound and can advance further if the market trades sideways.
Cosmetics quietly rebound on short covering.
Cosmetics is a quietly strong, deeply oversold sector with foreign/institutional accumulation and short-covering during earnings season, but media attention is low because investors are focused on autos and chips.
Shipbuilding uptrend intact; watch new orders.
Shipbuilding remains a favored sector; leader HD Hyundai Heavy Industries is only pausing, and if new orders or earnings confirm, related shipbuilding names can trade higher.
Power equipment demand remains structurally strong.
Power equipment remains strong because of structural electricity demand; the sector stays attractive even as other areas rotate.
Geopolitical dips remain S&P 500 buying opportunities.
Geopolitical risk has repeatedly become a buying opportunity under Trump's TACO pattern; the S&P 500 reclaimed its 10-day average and is supported by strong GDP, AI capex, fiscal stimulus, and expected Fed easing, so dip-buying remains appropriate.
Intel guidance weak; watch pullback support.
Intel's 4Q beat but 1Q guidance disappointed, mainly on supply constraints, not demand; the stock needs to hold its prior low and investors should wait for pullbacks rather than chase.
Tesla bottoming; 500 breakout could trend.
Tesla is forming a bottom/reversal with a news trigger; if it clears overhead resistance and the prior $500 high, it can create a November-style uptrend.
Meta only bottoming, not trend reversal.
Meta's rebound is only an oversold double-bottom confirmation and has not reversed the downtrend; it needs more confirmation before becoming a trend trade.
Mega-cap tech may catch up.
Small caps and lower-quality stocks have led, so large-cap tech may now catch up; Alphabet has the best flow, while Amazon, Microsoft, and Nvidia are basing.
Nvidia bottoming; needs bullish confirmation.
Nvidia is trying to bottom but still needs a large bullish candle to confirm; the risk/reward is improving but not yet a clean breakout.
SK hynix lags Micron and can catch up.
The memory super cycle is broadening from HBM into legacy DRAM as AI infrastructure demand grows; supply discipline supports pricing, and Samsung Electronics, SK hynix, and Micron are the key IDM beneficiaries, with Samsung raising some memory prices up to 80%.
Defense demand strong on geopolitical tension.
Greenland/geopolitical tensions keep defense and military demand in focus; Korean defense names such as LIG Nex1 can be expected to move with the global defense/aerospace strength.
POSCO lithium production improves earnings.
POSCO Holdings' Argentina lithium investments are moving into production this year/next, improving earnings as the battery supply chain recovers.
Samsung SDI leads solid-state battery theme.
Solid-state batteries are the key investment focus because robots and EVs need safer, lighter, higher-density batteries; Samsung SDI is the leading listed solid-state battery play and already moving first.
KEPCO not a clean nuclear play.
JP Morgan downgraded Korea Electric Power to neutral, arguing it is not a clean nuclear construction play; when KEPCO rallies, related nuclear/construction names often lag, so KEPCO is less attractive as a nuclear proxy.
Tesla robotaxi hopes persist despite delays.
Elon Musk's Davos comments point to robotaxi expansion and eventual humanoid sales, keeping autonomous driving expectations alive for Tesla, though timelines keep slipping and credibility concerns remain.
Autonomous driving theme remains active.
Autonomous driving and robotaxi expectations should continue through the year via Tesla, Nvidia-Benz, and Hyundai-Nvidia collaborations, even as competition with Waymo and Amazon intensifies.
Ukraine reconstruction theme on peace talks.
Trump-Zelensky talks and planned three-party discussions raise the chance of Ukraine ceasefire/reconstruction progress, putting reconstruction-exposed names such as Hyundai E&C and HD Hyundai Construction Equipment in focus.
Nvidia China export blocked; monitor policy.
Nvidia's H200 China export approval faces Congressional resistance, but market expectations are already low; the key is whether the Trump administration intervenes to support exports, so this remains a monitoring event.
Korean chip equipment favored on rotation.
As large memory names take profits, Korean semiconductor equipment and materials stocks should stay relatively favored on rotation and the ongoing memory upcycle.
Space economy investment keeps growing.
Davos discussions on space data centers and Europe joining the space economy support the space/aerospace theme; individual issues like Rocket Lab can be noisy but sector investment is growing.
AI power bottleneck fuels electricity demand.
AI data centers create a power bottleneck; Trump and Jensen Huang both emphasize energy shortages, requiring more electricity generation and efficiency, which supports power infrastructure.
Policy shifts from renewables to nuclear/gas.
The Trump administration is cutting $84bn of clean-energy loans and redirecting support toward nuclear and fossil fuels; this is negative for solar/wind/renewables and positive for nuclear and natural gas.
Policy shifts from renewables to nuclear/gas.
The Trump administration is cutting $84bn of clean-energy loans and redirecting support toward nuclear and fossil fuels; this is negative for solar/wind/renewables and positive for nuclear and natural gas.
Samsung SDI re-rates on solid-state narrative.
Solid-state batteries are becoming the core narrative for humanoid robots and safety; Samsung SDI broke to a 52-week high as institutions had to fill empty positions, with PBR near 0.8 and EPS still weak, so the move is multiple re-rating.
Alteogen trend broken; avoid.
Alteogen's trend broke below long-term support and the royalty math leaves limited valuation upside; the weak technical rebound suggests the stock is no longer a clean biotech leader.
Prefer other biotech over Alteogen.
The problem is Alteogen-specific, not all biotech; investors should prefer other Korean biotech names with technology-export/licensing expectations rather than buying Alteogen's weak rebound.
ESS and robot demand lift batteries.
AI data-center power demand should ultimately boost renewables plus ESS, and ESS uses batteries; robot/cybercab battery demand adds another leg, so the Korean battery/ESS story is not over.
LGES benefits from Tesla and robot batteries.
LG Energy Solution supplies cylindrical batteries to Tesla and potentially Optimus; the backlog remains huge despite cancellations, and robot battery momentum can support the stock.
Seojin System earnings justify 50% upside.
Seojin System broke to a 52-week high with strong ESS-linked earnings; operating profit forecast roughly doubles from 160bn won in 2026 to 320bn won in 2027, suggesting a valuation path toward 3tn won from 1.7tn won, so buy on dips.
Korea Aerospace offers breakout risk/reward.
Korea Aerospace has NASA-related certification news and pulled back to moving averages; if it breaks out again, risk/reward is attractive.
LS governance pressure may lift holdcos.
Minority shareholder pressure over LS's subsidiary listing is challenging old holding-company governance; if LS responds or succeeds, it could pressure other conglomerates to improve and support holding-company valuations.
Brokerage earnings benefit from market boom.
Mirae Asset Securities benefits from the domestic market boom, customer deposits, trading and FX fees, extended trading hours, and the SpaceX IPO theme; brokerage earnings should improve.
Wait for Hyundai Motor moving-average pullback.
Hyundai Motor faces heavy foreign/institutional selling while retail buys, making the short-term flow look poor; wait for pullbacks to the 5-day or 10-day moving average rather than chasing.
Robots need Hyundai leadership to revive.
The robot sector is overheated and Hyundai Motor is its leader; if Hyundai falls, robot stocks generally will not work, but if Hyundai resumes rising, robot names can revive, especially surgical or specialized robots.
Gold and silver stay bid.
Gold and silver are not falling even as geopolitical risk fades, showing a strong commodity bid; they remain part of a rotating commodity complex.
Lithium rebound supports Albemarle.
Lithium carbonate has resumed its uptrend after China's supply-side reform reduced competition; Albemarle is up sharply and the commodity rotation remains strong.
Gas spike helps Korean NCC chemicals.
Cold weather spiked natural gas, which hurts ethane-based ECC economics and makes Korean naphtha-based NCC more competitive; Lotte Chemical and Daehan Synthetic Fiber may twitch as a result.
Policy and InterBattery lift solid-state batteries.
Government support for a Korean IRA and battery-sector structural reform could help KOSDAQ battery names; solid-state battery stocks also have a seasonal catalyst into InterBattery in March.
OCI attractive away from resistance.
OCI Holdings is a cleaner solar/polysilicon play as China-related restrictions support the sector; buy when it is away from the 125,000-130,000 won resistance, or trade a confirmed close above it.
Robot security need lifts Suprema.
As robots enter homes and factories, hacking and safety risks create a security need; KB named Suprema as a key security partner in Hyundai Motor's robot ecosystem, driving its shares sharply higher.
ITCEN benefits from stablecoin policy.
Stablecoin policy expectations are building, and ITCEN Global is a cash-generating play with good 4Q/1Q earnings prospects.
NewFlex gains robot FPCB demand story.
NewFlex's FPCB technology is being linked to robot applications, adding a new demand story and driving fresh strength in the shares.
This 815 Money Talk (815머니톡) video, published January 23, 2026,
features Park Hyun-sang, Hwang Yoo-hyun, Lee Ju-hyeon, Min Jae-gi
discussing EWY, Korean small/mid-cap equities, 005380.KS, KARS, 006400.KS, 066970.KS, KORU, Korean shipbuilding sector, Korean Power Equipment Sector, SPY, INTC, TSLA, META, MAGS, NVDA, 000660.KS, MU, 005930.KS, 079550.KS, ITA, 005490.KS, 015760.KS, ARKQ, 000720.KS, HD Hyundai Construction Equipment, Korean semiconductor equipment/materials, Space/aerospace sector, XLU, SOLAR, URA, UNG, 196170.KQ, Korean biotech ex-Alteogen, Korean battery/ess sector, 373220.KS, 178320.KQ, 047810.KS, 006260.KS, 006800.KS, ROBO, GLD, SILVER, ALB, Lithium carbonate, 011170.KS, Daehan Synthetic Fiber, 010060.KS, 236200.KQ, 094840.KQ, 124500.KQ, 095270.KQ.
48 trade ideas extracted by AI with direction and confidence scoring.
Speakers:
Park Hyun-sang,
Hwang Yoo-hyun,
Lee Ju-hyeon,
Min Jae-gi
· Tickers:
EWY,
Korean small/mid-cap equities,
005380.KS,
KARS,
006400.KS,
066970.KS,
KORU,
Korean shipbuilding sector,
Korean Power Equipment Sector,
SPY,
INTC,
TSLA,
META,
MAGS,
NVDA,
000660.KS,
MU,
005930.KS,
079550.KS,
ITA,
005490.KS,
015760.KS,
ARKQ,
000720.KS,
HD Hyundai Construction Equipment,
Korean semiconductor equipment/materials,
Space/aerospace sector,
XLU,
SOLAR,
URA,
UNG,
196170.KQ,
Korean biotech ex-Alteogen,
Korean battery/ess sector,
373220.KS,
178320.KQ,
047810.KS,
006260.KS,
006800.KS,
ROBO,
GLD,
SILVER,
ALB,
Lithium carbonate,
011170.KS,
Daehan Synthetic Fiber,
010060.KS,
236200.KQ,
094840.KQ,
124500.KQ,
095270.KQ