Software stocks will rebound from AI scare, says D.A. Davidson's Gil Luria
Speakers
Gil Luria
— Technology Strategist at D.A. Davidson
Summary
Gil Luria of D.A. Davidson tells Fast Money that the selloff in software stocks on AI disruption fears is overdone. He favors selectively buying high-quality, recurring-revenue software companies and singles out Adobe as a cheap stock with resilient growth. He also warns Oracle is overextended and overborrowed after committing to OpenAI infrastructure, leaving its credit and equity risk elevated.
- Gil Luria says AI has not disrupted any software company and the AI scare narrative is not supported by current fundamentals.
- He argues high-quality software companies still offer recurring revenue, high incremental margins, and double-digit growth at attractive cash flow multiples.
- He is not calling a bottom on all software, instead favoring selective buying of good companies whose stocks keep falling.
- Adobe is his specific bull case: growth held up better than the software universe and the stock trades at low-teens earnings and cash flow multiples.
- Oracle is described as overextended for OpenAI, overborrowed, and close to the bottom rungs of investment grade while needing more debt.
- The segment frames the main market implication as a potential software rerating once negative AI sentiment fades, while Oracle credit risk remains a concern.
Ideas
Select software stocks due for rerating.
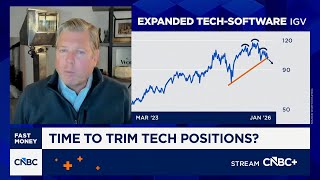
Gil argues the AI scare in software is overdone: high-quality software companies still have recurring revenue, high incremental margins, and double-digit growth, but many now trade at low-teens to 20s cash flow multiples. He is not calling a bottom for all software, but says selectively buying good software companies whose stocks keep falling should lead to a rerating once the negative AI narrative fades, especially since AI has not disrupted or dislocated any software company yet.
Adobe cheap, AI fears overblown.
Adobe's growth has held up better than the overall software universe despite AI fears, with growth decelerating only from about 12% to 10-11% over three years because its recurring revenue is deeply embedded in marketing organizations and agencies. The stock trades at low-teens multiples on earnings and cash flow; if Adobe keeps growing around 10%, it is unsustainable for shares to stay this cheap, and the negative AI narrative lacks evidence that it is losing business.
Oracle overborrowed; credit risk elevated.
Oracle overextended itself for OpenAI and overborrowed to build AI infrastructure after OpenAI promised the moon to many partners. The company is now approaching the bottom rungs of investment grade and the ceiling of its debt ratio, yet still needs to borrow more to meet commitments, putting it in a real bind. The stock has fallen significantly and its debt trades at a discount, so investors should avoid the credit and equity risk.