The Key Takeaways From Netflix's Q4 Results and Forecast
Summary
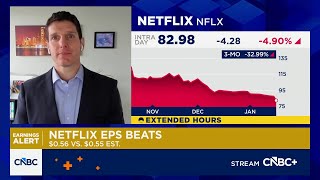
David Joyce of Seaport Research Partners discussed Netflix's fourth-quarter results on Bloomberg The Close. He noted the company beat the December quarter but gave a lighter margin guide, sending shares lower after hours. Joyce maintained a buy rating, arguing the selloff is overdone and pointing to advertising growth, international expansion, and content/theatrical strategy. He also addressed the potential Warner Bros. Discovery deal and Netflix's show-me execution phase.
- Netflix beat Q4 results, but revenue guidance was only slightly better and margin guidance was lighter.
- Shares traded lower after hours on a sell-the-news reaction.
- David Joyce has a buy rating and says Netflix stock has fallen too much.
- Netflix advertising revenue is expected to roughly double in 2026; ad-tier, live programming, and sports strategies are seen working.
- Long-term subscriber growth is expected internationally, especially in Asia, while the U.S. is mature.
- Content spending is considered necessary, with the Sony pay-one deal through 2032 supporting content supply.
- Theatrical and IMAX releases like Narnia could boost engagement, marketing, and awards.
- The potential Warner Bros. Discovery deal remains uncertain and may take 12 to 18 months to bear out.
Ideas
Up Next

This Bloomberg Markets video, published January 20, 2026, features David Joyce discussing NFLX. 1 trade idea extracted by AI with direction and confidence scoring.
Speakers: David Joyce · Tickers: NFLX