Ideas
Asian tech and chip supply chain favored.
This is not a year to blindly buy Nasdaq or Nvidia; Asian tech is surging at a discount to Nvidia multiples, with money looking for value and upstream supply-chain exposure. A lot of the action is in memory chips, where investors focus on a possible supply shortage this year, and chipmakers are preferred over software/AI agents.
Industrial metals see supply bottlenecks.
Investors are looking upstream for supply-chain bottlenecks, and industrial metals are part of that story. Silver and copper have had strong starts to the year because investors are focused on where bottlenecks could appear and may be underpositioned in these alternatives.
Peter
Global Macro Strategist, RBC Capital Markets
14:32
Asia offers cheap diversification from U.S.
Diversification into Asia is a key theme because investors see perceived overinvestment in the U.S. as a risk. Asian risky assets look cheap and currencies are also cheap, making Asia a good angle for international investors.
Peter
Global Macro Strategist, RBC Capital Markets
20:48
Asian currencies offer diversification and strength.
The best individual FX strength is likely in Asia. Perceived overinvestment in the U.S. makes diversification attractive, Asian currencies look relatively cheap, the yuan is below 7, other regional currencies are doing well, and RBC is a proponent of Asian currency strength.
Peter
Global Macro Strategist, RBC Capital Markets
21:32
EUR/USD higher on weaker dollar.
Because of diversification and U.S. trade policy, the dollar should weaken over time, pushing EUR/USD higher. This is not primarily a strong European story but more a weaker-dollar and stronger-Asia dynamic.
Peter
Global Macro Strategist, RBC Capital Markets
21:32
EUR/USD higher on weaker dollar.
Because of diversification and U.S. trade policy, the dollar should weaken over time, pushing EUR/USD higher. This is not primarily a strong European story but more a weaker-dollar and stronger-Asia dynamic.
Copper fundamentals support a strong market.
Copper fundamentals have been building toward reduced oversupply and deficits, with about 7% of world production offline by end-2025. Prospective U.S. tariffs on refined products and strong demand from electrification, data centers, AI, EVs and power infrastructure create the makings of a good market; she favors the fundamental story over short-term tariff noise and sees copper producers/equities as an additional way to get leverage.
Gold gains on paper currency debasement.
Geopolitics is another factor, but the core driver is the loss of purchasing power in paper currencies. Gold is catching up to where it should be in purchasing-power terms and should continue higher over decades, probably at an accelerated rate.
Silver fundamentals support higher prices.
Silver's move is not just a London-New York shipping event; she returns to underlying fundamentals, with producers making substantial cash flow and trading at low multiples, supporting the market.
Gold miners offer low-multiple cash flow.
Gold producers are generating enormous cash flow with roughly 50% margins and are trading at the lowest multiples she has seen in her career. Companies offer extra return potential through growth, dividends and M&A, and a diversified equity solution should deliver superior outcomes versus only holding the metal.
Equity returns should beat consensus.
Consensus 2026 equity earnings growth of 9% looks relatively cautious given a strong growth context, monetary easing feeding liquidity and U.S. fiscal easing. Returns should be higher than consensus, so investors should have a more bullish bias.
Crowded euro longs risk downside.
Leveraged funds were very long the euro at end-2025, comparable to the 2018 peak, which preceded a two-year decline in the euro trade index. That positioning makes the crowded bullish EUR stance worrying, and over the next year she sees euro downside as much of the bullishness is already priced relative to growth and bank expectations.
U.S. large-cap AI trade persists selectively.
The AI trade should be barbelled across the fast-moving digital layer and the physical layer financing the AI buildout. The physical IT layer is longer-duration and inflation-linked and is probably the greater opportunity set while maintaining U.S. equity exposure.
Software and cloud are key AI areas.
Within AI/tech, software and cloud computing are key areas of focus because investors will discriminate on earnings sustainability and profitability, and these pockets can improve profitability.
European equities benefit from cyclical upturn.
There is a meaningful case for European equities to bet on a global cyclical upturn. Europe is well-positioned, with fiscal impulse, ECB rate cuts transmitting through the credit impulse, and German infrastructure/defense spending supporting growth, while U.S. AI exposure can be barbelled with regional opportunities.
European banks cheap with positive impulse.
European banks should strongly outperform. They are cheaper relative to U.S. banks, and the backdrop of fiscal impulse, ECB rate cuts and an improving credit impulse supports them.
European defense supported by spending.
Infrastructure and defense spending, especially from Germany, is a key pillar of European growth and should support defense companies alongside industrials and banks.
European industrials benefit from fiscal spending.
German infrastructure and defense spending is a key growth pillar that should support European industrials and other cyclicals.
European luxury favored on healthy consumer.
At the margin, Nuveen is leaning into European luxury because the consumer is healthy, the labor market is solid, real incomes are rising, inflation is near 2%, and they want greater exposure to cyclicals.
European auto/industrial chips see read-across.
There is a positive read-across from Microchip's raised forecast to European chipmakers exposed to auto and industrial end-markets, specifically Infineon and STMicro, which moved about 2%.
NVIDIA Rubin and AI stack drive growth.
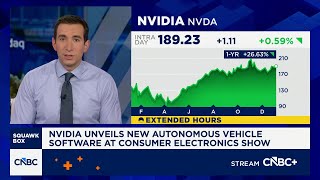
Rubin is in full production and customers will soon be able to try it. NVIDIA is no longer just a chip company but builds entire AI systems and a full stack, and the next wave extends into robotics and autonomous driving, with its autonomous driving product expected on roads in the first quarter.
Brent target remains below current levels.
JPMorgan has a Brent target of $58 for end-2026, below current levels, though the view was set before the Venezuela escalation and needs reassessing. Venezuela plus U.S. influence could affect up to 40% of crude production, so the situation is monitored closely.
This Bloomberg Markets video, published January 06, 2026,
features Valerie Tytel, Peter, Evy Hambro, Skyler Montgomery Koning, Laura Cooper, Chloe Meley, Jensen Huang, Matthieu
discussing Asian technology stocks, SMH, COPPER, SILVER, AAXJ, Asian currencies, EUR/USD, UUP, Copper mining equities, GLD, GDX, VT, AI-SECTOR, IGV, SKYY, VGK, EUFN, EUAD, European industrials, European luxury, IFX.DE, STMPA.PA, NVDA, BNO.
22 trade ideas extracted by AI with direction and confidence scoring.
Speakers:
Valerie Tytel,
Peter,
Evy Hambro,
Skyler Montgomery Koning,
Laura Cooper,
Chloe Meley,
Jensen Huang,
Matthieu
· Tickers:
Asian technology stocks,
SMH,
COPPER,
SILVER,
AAXJ,
Asian currencies,
EUR/USD,
UUP,
Copper mining equities,
GLD,
GDX,
VT,
AI-SECTOR,
IGV,
SKYY,
VGK,
EUFN,
EUAD,
European industrials,
European luxury,
IFX.DE,
STMPA.PA,
NVDA,
BNO