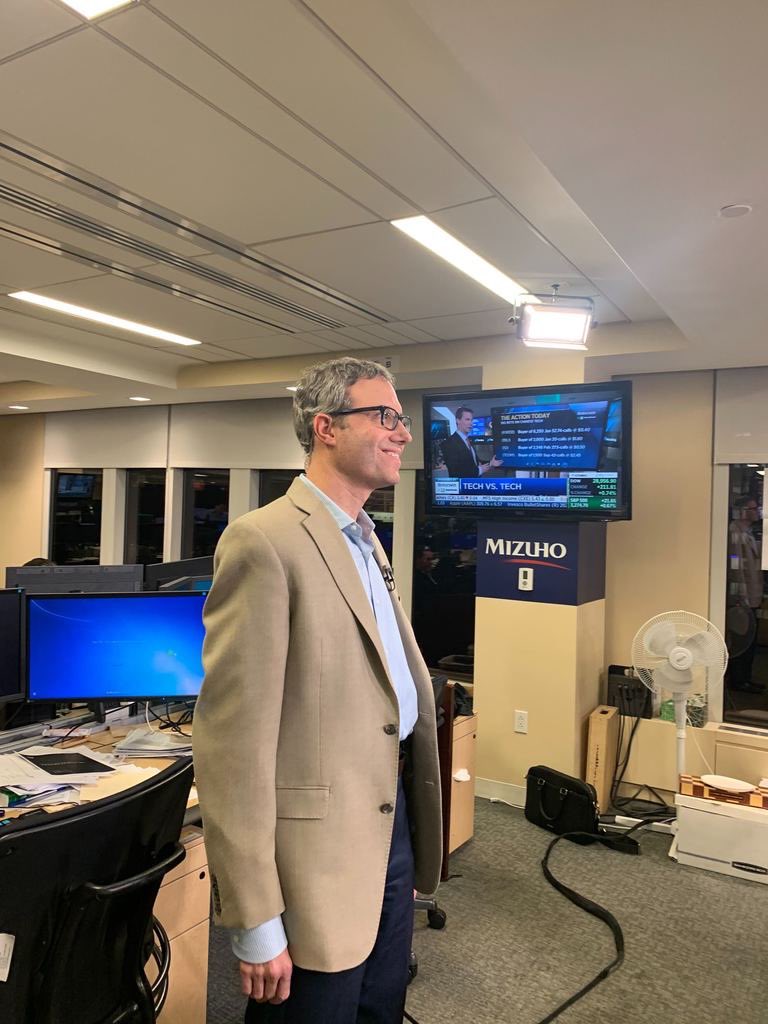
Greg Moskowitz

Analyst, Mizuho
· tracked since Feb 2026
Calls
2
Win Rate
100.0%
return
+15.0%
Calls 2 3 Posts tracked · 0.0/day
Calls
7d 0
30d 0
90d 1
Win Rate 100% Long 2 Short 0
Win Rate
7d 100%
30d 50%
90d 0%
Average Return +15.0% Long Return +15.0% Short Return -
Average Return
7d +6.3%
30d +3.0%
90d -11.0%
Visual Insights Log in to see more
Result
Result
Sort
Theme Stance
Ticker
Side
Mentions
First Call
Call Price
P&L
Thesis
Theme
Source
Long
Jul 30
$447.82
+10.3%
Microsoft Azure re-accelerating strongly
Microsoft Azure revenue growth re-accelerated to 43% year-over-year, beating expectations and guiding for 45% next quarter, demonstrating strong cloud momentum and competitive positioning, dispelling doubts about losing mojo. Accounting change for capex does not alter actual spending plans.
Hyperscalers
Long
Feb 26
$199.47
+19.7%
"Agent force... really picked up. It was at 540 million in annualized recurring revenue last quarter. It's now at 800 million." Additionally, the company has authorized a "$50 billion" buyback, signaling they see "uncommon value." The market is selling the stock based on a fear narrative (AI kills seat-based SaaS), but the data shows the new AI product (Agent Force) is compounding rapidly (nearly 50% sequential growth). Combined with a massive buyback floor, the stock is undervalued relative to its future margin potential and expected revenue reacceleration in the second half of the fiscal year. Long CRM as a contrarian play on AI adoption; the "cost" of software production is dropping while the high-value AI agent revenue is ramping up. The "Marketing and Commerce" segments are decelerating and are not expected to pick up in 2026, acting as a drag on overall performance. The "negative narrative" regarding AI disruption may persist for several quarters before the reacceleration is visible in earnings.
AI Software
Showing 2 of 2 calls · sorted by mentions

Greg Moskowitz has 2 trade ideas tracked on Buzzberg across 2 tickers since February 2026. Most covered: CRM, MSFT.

Historical call returns are modeled from recorded ideas and stored prices, not actual brokerage portfolio returns. Check the evaluated call set and horizon; past results do not establish future prediction accuracy. Explore our data and methodology
